November Market Data Comes in Mixed for Greater Palm Springs Real Estate
Check out the recap of the Greater Palm Springs real estate market to see the current state of the desert market.
Greater Palm Springs Real Estate Market Analysis – November 2025
Although interest in Greater Palm Springs real estate remains high, the month of November saw a slight dip across the primary metrics we track. Despite the influence of the holiday season and other factors, numerous indicators indicate that the market remains robust and stable as we approach the final month of 2025. The numbers and analysis below represent the entire Coachella Valley region. If there is a city, neighborhood, or community you are interested in learning more about, connect with your local Bennion Deville Homes real estate professional. We will unlock possibilities for you.
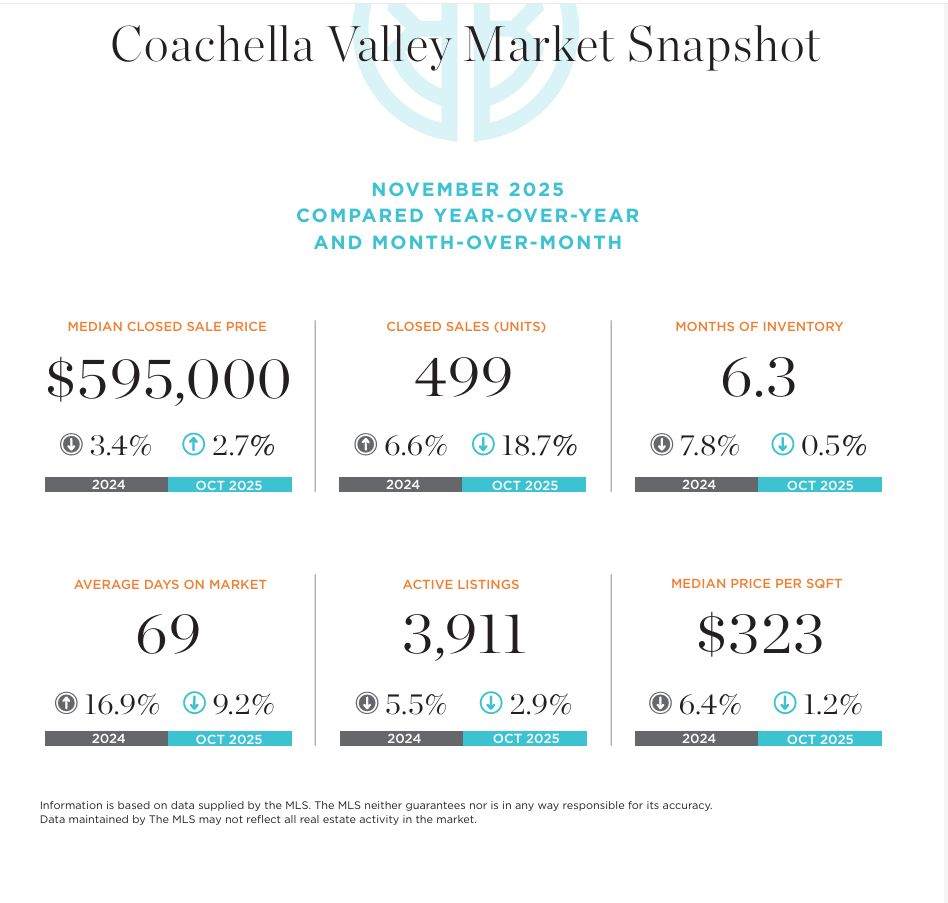
The November market stumbled slightly, notching small declines across almost all tracked categories when compared both monthly and annually. Most of the monthly dips can be attributed to a typical seasonal slowdown in November and usually December, as buyer and seller activity pulls back due to the holidays. Annually, the market saw more home sales, a dip in the median sale price, and a faster sale pace. The listing discount also deepened compared to both periods, indicating sellers are having to become more realistic with their pricing and expectations as inventory recovers and buyers have more choices to consider.
Despite mixed results and slight backward momentum, the market is primed for a strong season. The numbers represented are still robust, including active inventory hovering just under 4,000 homes for sale, months of inventory that strike a balance for both buyers and sellers, and a receding but still lofty median sale price. Because of the general balance market-wide, both buyers and sellers are in excellent positions to accomplish their goals.
Buyers can be satisfied knowing the listing discount has grown, inventory remains high, prices are improving in their favor, and the slower sale pace means serious sellers may be more willing to negotiate if timing is a factor in their decision. Sellers should be comforted by still-strong home prices and solid demand from buyers to purchase homes in the desert. In any market, properly prepared and priced homes will sell quickly and fetch top dollar. If you are interested in exploring your options, we would be honored if you made a Bennion Deville Homes agent part of your process. We have the resources, information, and network to help with your real estate needs.
November saw 499 homes exchange owners in the Greater Palm Springs Area, a 6.6% annual increase but an 18.7% monthly drop. The median sale price of a home capped the month at $595,000, a 3.4% drop year-over-year but a 2.7% increase compared to the previous month. Additionally, the median price per square foot ended the month at $323, a 6.4% decline compared to last November and a 1.2% dip month-over-month. The sale pace, noted as average days on the market, finished at 69 days, a 16.9% increase (slower) year-over-year, but a 9.2% monthly decrease (faster). The listing discount was 3.5%, or 96.5% of the list price, calculated by dividing the sale price by the list price and subtracting from 100, reflecting a 0.5% cut from last year and a 0.4% decrease from the prior month. November finished with 3,911 active homes for sale, a 5.5% annual decrease and a 2.9% monthly dip. Overall, there is a 6.3-month supply of homes to meet market demand, a 7.8% drop compared to the prior year, and a 0.5% decrease from October. A 6-month supply of homes is traditionally considered a balanced market, so current market conditions are relatively neutral for buyers and sellers.